Most working adults in the U.S. get their health coverage through an employer group plan. Because employers share the cost of premiums and can negotiate group rates, employer plans are often more affordable than buying an individual policy on the open market.
What to look for in an employer plan
- Monthly premium contribution taken from your paycheck
- Deductible and out-of-pocket maximum for the plan year
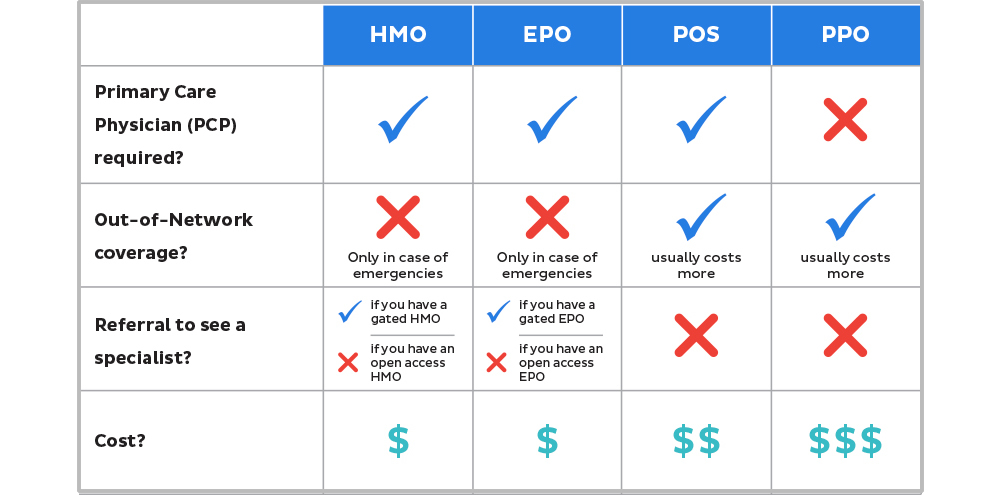
- Whether the plan is an HMO, PPO, EPO, or POS
- Whether dental and vision are bundled in or offered separately
- Open enrollment dates and any qualifying life events that let you change plans mid-year
When an employer plan isn't enough
If you're a part-time employee, between jobs, or your employer doesn't offer coverage, you still have options: an ACA marketplace plan, short-term insurance, or COBRA continuation coverage from a previous employer. A U Save MD consultant can walk through which option costs less over the year once premiums, deductibles, and coverage gaps are all factored in.